What Is a Credit Builder Loan? How It Works & Can It Improve Your Credit Score?

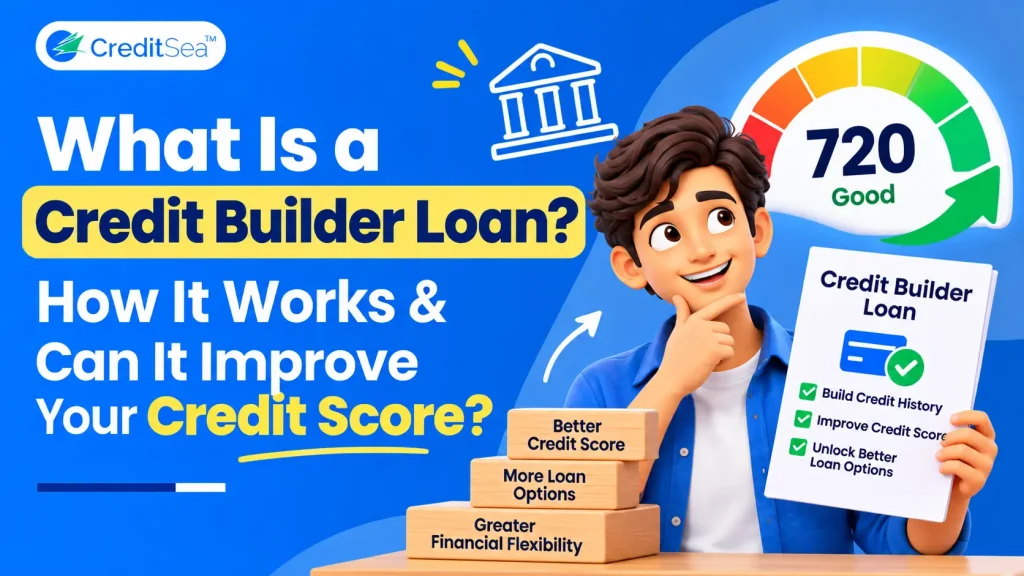
A credit builder loan is a type of small installment loan that is designed to help you to build your credit score by establishing a positive credit history by making some regular payments. It is very useful for the people who are new to borrowing, and if any have a little or no credit history, it helps to create good repayment habits.
Making payments on time can build a positive credit history if the lender reports the accounts and its repayment activity to credit bureaus on time. So, understand that taking a credit builder loan does not guarantee an increase in your score.
What Is a Credit Builder Loan?
A credit builder loan is a type of loan that is designed for the user to create a positive payment history. It is for the people who want to strengthen their credit history.
A credit builder loan is helpful for the people who have little or no credit history and who intend to establish a record of a responsible credit history. They want to take a loan in the near future and want to improve their credit profile over time. Understand that a credit builder loan is an opportunity to demonstrate that you can handle the borrowing with responsibility and you can repay the amount on time.
A credit builder loan is not just a single or a standardized loan category that has identical features across all the lenders. The structure of the product can vary, so the borrower should carefully check the lender’s terms and conditions and confirm that these repayments are being reported to credit bureaus.
How Does a Credit Builder Loan Work?
There are certain steps in which a credit builder loan works:
Step 1: Apply for the loan.
The borrower starts by applying for the loan through a lender, and it provides the information and documents. The approval for that depends on the eligibility criteria of the lender.
Step 2: Review the terms of the loan.
Check all the details, such as the loan amount, interest rate, repayment schedule, and the total amount that needs to be repaid before you accept the payment.
Step 3: Make the repayments on time.
Before you take up the loan, first practically assess if you will be able to repay this loan comfortably or not. Whether this will fit in your financial budget or not. You need to clear each installment before the due date arrives. A consistent repayment behavior will help you establish a positive credit record if the account is being reported to a credit bureau.
Step 4: Monitor your credit report.
From time to time you need to check whether the loan and its repayment history are appearing on your credit report and there are no errors in it, although the changes in the score might take some time and it is not guaranteed.
Can a Credit Builder Loan Improve Your Credit Score?
Yes, a credit builder loan can help to improve your credit score, but the outcome of that completely depends on your repayment behavior, credit history, and the scoring model that has been used. There are a few steps that can increase your credit score.
- Timely repayment: Paying your EMIs consistently on time will help you build a positive repayment history.
- Building a credit history: If you have no credit history yet, it will help you to create a record.
- Overall credit behavior: Everything that you have been doing financially can have an impact on your credit profile, late payments, defaults.
A credit builder loan is a way to build a credit history, but that comes with the value of responsible borrowing and repayment behavior, not just simply taking a loan.
Who Should Consider a Credit Builder Loan?
A credit builder loan can be considered if you are:
- A first-time borrower: If you are a first-time borrower, which means you have never taken a loan or a credit card, when you have little or no credit history
- A young salaried professional: If you have just started on learning and you want to establish a credit track record
- Someone with a limited credit history: If you use credit only occasionally and you want to build a more consistent record of repayment.
- Someone who is rebuilding your credit profile: You want to demonstrate a better habit of repayment and create a positive repayment.
What are the benefits of a credit builder loan?
| Benefits | What is it? |
| It helps you to build a credit history. | Reporting the loan may help first-time borrowers establish a credit history. |
| Supports periodic payments. | A fixed repayment schedule can help the borrower to form a regular payment habit. |
| May assist with future credit applications | There’s no guaranty you’ll be approved, but a good credit history can be a plus in the eyes of lenders when they look at future applications. |
| It promotes credit awareness. | Monitoring of repayment and reviews of credit reports can lead to improved financial behavior. |
What Are the Risks or Things to Check Before Applying?
The possible risks and things to check on before applying:
- Interest and fees: There are costs that are involved for taking up a loan, which include the processing fee, interest, and other applicable charges
Missed payments: If you miss a payment, there will be late payment charges, as well as it will affect your credit profile.
Credit bureau reporting: The activity that you make in your credit is reported by the lender to the credit bureau; it carries your information on credit. If you have missed any payment or you have an increased credit limit, all of these factors contribute to your credit score.
Affordability: First check if the loan clearly fits in your budget or not, and whether you will be able to comfortably repay the loan or not.
Credit Builder Loan vs. Personal Loan
| Features | Credit builder loan | Regular personal loan |
| Main purpose | A credit builder loan helps establish or strengthen credit history. | These can be used to cover planned or unexpected expenses. |
| Typical audience | People with limited or no credit history, depending on eligibility | Borrowers who meet the lender’s eligibility criteria |
| Repayment | Scheduled repayments under the loan agreement | Scheduled EMIs under the loan agreement |
| Credit score impact | May help build credit if repayments are reported and managed well | May also help build credit if reported and repaid on time |
| Main consideration | Confirm reporting, costs, and product structure. | Compare interest, fees, affordability, and total repayment |
How Long Does It Take to Improve Your Credit Score?
The borrowers may expect the results to improve immediately, so understand that building a credit takes time. The credit bureaus’ updates completely depend on when the lenders report about the account information. Some consistent payments over time will help you build a positive credit history. There is no specific fixed timeline that the score will be improved because every person’s credit profile is different. You should check your credit report periodically to confirm that your repayment information has no errors.
The RBI has issued directions on how frequently the credit information will be reported by the lenders, but reporting updates does not mean that the credit score will be improved by a particular date.
How to build a fixed credit score from scratch?
To build a credit score from scratch as a beginner, first you need to open a credit account and show the lenders that you can pay back the money more reliably.
To build a credit score from scratch as a beginner, you need to open your first reported credit account and show lenders that you pay back money reliably.
Check Your Credit Options with CreditSea
If you’re just getting started on your credit journey, knowing what your borrowing options are is an important first step. CreditSea is a digital lending platform for salaried individuals, which offers an online application process for eligible users to explore loan options. Before applying, please read the eligibility criteria, interest rate, fees, and repayment terms to help you make an informed decision.
Must Read – CIBIL Score Explained: How It Works & How to Improve It
FAQs
What is a credit builder loan?
A credit builder loan is designed to help the borrowers establish or strengthen their credit profile with the help of scheduled payments. While its features and reporting practices completely depend on the lender and its product.
Is a credit-builder loan a good idea?
A credit builder loan is generally a good idea if you have just started earning and if you have little or no credit history, and you genuinely intend to build a healthy credit score.
Do you get the money back from a credit-builder loan?
Yes, you can get money from a credit builder loan, from an accumulated principle balance back at the end of the credit builder loan without any applicable charges or interest.
Can a credit builder loan improve my CIBIL score?
Yes, it can help improve the CIBIL score if the lender reports to the credit bureau and you make the repayments on time. But an improvement in your CIBIL is not guaranteed.
How to fix credit?
You can fix your credit from scratch by paying your EMIs on time, keeping your credit card balances low, and avoiding filling multiple applications at once. Consistent financial habits can help you improve your credit score with time.
Final Takeaway
In conclusion, a credit builder loan will help you establish a credit history, but understand that a consistent repayment matters more than just simply opening up an account. It’s important to handle borrowing responsibly, and a borrower should always first check the costs and reporting practices before applying for a loan.