What Is CKYC? How to Find and Use Your CKYC Number

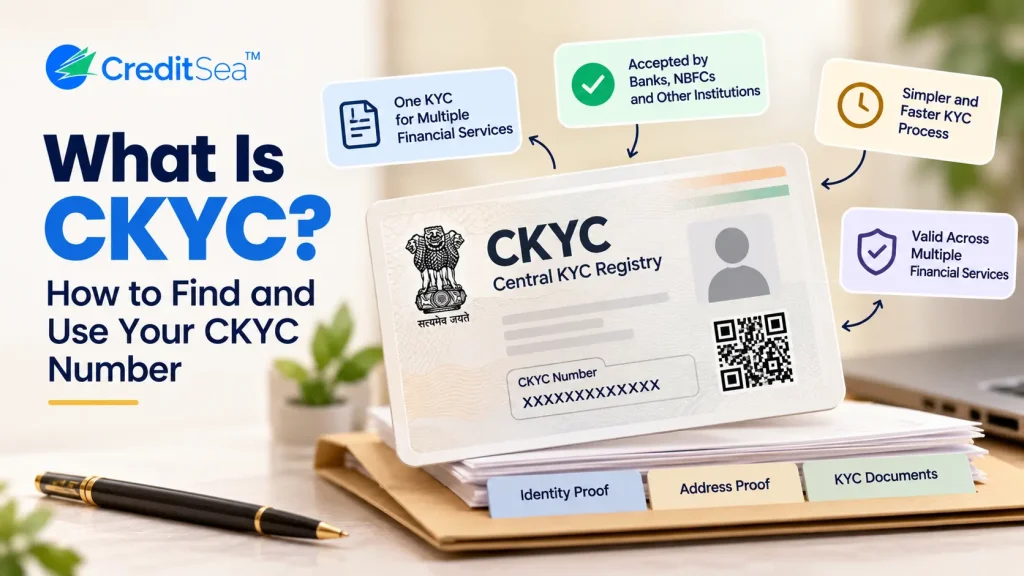
You might wonder that when you apply for a new bank account, an insurance policy, or an investment account, you might have to submit the same personal details and the same identity documents again. And you have already completed your KYC with another financial institute. You might wonder why the process cannot be more simple. This is where your CKYC comes in. CKYC stands for Central Know Your Customer. In India, it is a centralized system where all the KYC records are stored digitally. So once your KYC details are registered, you receive a unique 14-digit Central Know Your Customer number, which is called a KYC identifier. So the eligible financial institution can use this number to retrieve your existing KYC record and subject to applicable rules. So in this guide, we will discuss what a it means, how to find your CKYC, and how to use it, and what to do if you cannot locate your record.
What is CKYC
CKYC, or Central Know Your Customer, is a centralized system, centralized KYC system that is designed to make the customer identification easier in participating in other financial institutions. Think of CKYC, think of it like a digital folder that contains all of your KYC information and that authorized financial institutions can access whenever it’s needed. So, it helps the financial institution to access your KYC record instead of collecting all the information from scratch.
When you open a bank account, the bank asks you for your details like PAN card, identity proof, address proof and other details so that they can verify who you are. This is called KYC and it’s how the financial institution verifies your identity. And traditionally, customers have to provide all these details separately to different institutions. But CKYC helps to reduce the repetition by allowing the eligible institution to retrieve and take the KYC records from a central registry. They carry your KYC details digitally. The system is supported by the Central KYC Record Registry that is managed by the Central Registry of Securitization Asset Reconstruction and Security Interest of India, CERSAI. So, for example, suppose you complete your KYC while opening your bank account and your details are registered with CKYCRE, and later on you apply for an investment account with another institution. So the institution might not be able to retrieve your existing KYC record. So they will ask you to submit that information again. But if you are registered with Central KYC, they can take your information from there.
Note: This does not mean that you will never have to provide your documents again. Suppose if your details have been changed and your existing record is incomplete or any additional verification is required from your end, then the institution might ask for the updated information.
What is CKYC number
A CKYC number is a unique 14-digit number, which is given to you when your KYC record is registered in the Central KYC Records Registry, CKYCRR. And for example, that you join a library membership, and they provide you a membership number. Now this number helps you to find your membership details without creating a new membership record every time you visit. This is different from your PAN card. Your PAN card is a tax identification number, while your CKYC number identifies the centralization KYC record.
How to Find Your CKYC Number
Now you have completed your KYC with the bank, insurer, and another financial institution. So your CKYC number might already exist. There are some practical ways that you can look for that.
1. Check your previous KYC message. First, look at the SMS messages and emails you received after opening a financial account or completing your KYC. You should look for terms like CKYC, KYC Identifier, or Central KYC. your record was registered, your institution may have provided that number. Please be aware that the completion of your KYC does not guaranty that your CKYC record has been created. If you cannot locate the number go to the next step.
2. Contact your bank or financial institution. Contact your bank or insurance company, mutual fund, intermediary, or other financial institution if you completed your KYC there. Ask that your KYC details have been registered with CKYC-CRR and if they can help you with retrieving your CKYC number. And keep your identity details available to you for completing the verification process, and the institution might ask you to confirm your information such as PAN or date of birth, depending upon its process.
3. Check your financial account document. Look, go through the documents and communications that you have received when you opened an account or purchased a financial product. Some institutions might display CKYC identifiers in their digital banking services or include it in their document, such as account statement, passbook, or policy record, with appropriate masking. So the availability for that depends on the institution, and do not assume that every financial document will contain that.
4. Use the official CKYC website for guidance. Visit the official Central Know Your Customer portal to find the information about the Central Registry and its services. Don’t assume that every service that is available to the registered financial institution will also be available to the individual customer. And if you cannot retrieve your number through the available customer-facing option, you should contact the financial institution that has handled your KYC.
How to Use Your CKYC Number
What you ask for is your CKYC number. You can provide it to the financial institution that asks for your KYC identifier. So this is how it will help in different situations.
- Opening a bank account: When you apply for a bank account, the bank might want to use your CKYC number to retrieve your existing KYC record.
- Applying for an insurance policy: The insurer or other financial institution might want to use your Central Know Your Customer details as a part of their customer identification process. So this CKYC process can help them to reduce the need to resubmit the information that is already available in the central registry.
- Starting an investment account: When you open an investment account through participating in an institution, your CKYC number might help them, might help the institution to access your existing KYC record. Whether the additional document or verification are needed depends on the institution requirement and your situation.
So CKYC is not a credit score and it does not decide whether your loan will be approved or not. Lenders may also look at your income, ability to repay and other qualifying requirements. This may help you to streamline the identity verification process and help you to cut down on having to re-submit the same KYC information.
Difference Between CKYC and e-KYC?
CKYC and e-KYC are related to customer identification, but they are not the same thing.
It means Central know your customer, Which is a centralised system in India that stores customers KYC details deigitally, So that they don’t have to submit the same documents repeatedly.
While e-KYC (Electronic know your customer) is a digital method of verifying your identity. It is a paperless process that uses the latest technology to verify the customer identification digitally. eKYC specifically focuses on digital authentication, and it works using your Aadhaar number, authentication via one-time password OTP, or biometrics. And it is a paperless identification verification without seeing the customer in person.
FAQs
1. What is CKYC?
CKYC stands for Central Know Your Customer. This is a centralized system in India that stores all the KYC records digitally, and it helps the financial institution to retrieve the existing customer information.
2. How many digits is a CKYC number?
The standard CKYC number is a unique 14-digit identifier, which is assigned to the registered KYC record. It is the reference number that the financial institution can rely on whenever they want to find the information about the customer. Certain special amounts might have categories and have additional prefixes under the applicable registry guideline.
3. How can you find your CKYC number?
You can find your CKYC number by looking up your previous KYC related SMS messages, email and financial account document. You can contact your bank or financial institution where you have done your process of Central Know Your Customer and ask them to help you in retrieving the CKYC number.
4. Should I enter CKYC number?
No, you don’t have to do a new CKYC registration every time you use a financial institution. If your existing record for KYC is available and meets the applicable requirement, the institution may retrieve the information. If your details has been updated or your details needs to be updated, new registration or further verification might be required.
5. What is the difference between CKYC and eKYC?
eKYC is electronic identity verification whereas CKYC is the centralized system to hold the KYC record. They both serve the related purposes, but they are not interchangeable. eKYC is a digital process of doing KYC registration, while Central Know Your Customer is the central system that stores your KYC details.
Final Thoughts
A CKYC number can make all the things easier for the financial institution and for you also to access your existing KYC record, because it reduces your need to repeat the parts of the identification process again and again. So the first step is to check your previous financial institution, or contact the institution where you have completed your KYC, and you need to keep your information accurate and use the verified channel when you are sharing your personal details. And remember that CKYC simplifies the customer verification, but that does not replace every verification requirement. So if you are preparing to use a financial service, understand that your KYC detail is a useful step towards smoothing your application process.
Must Read – What Is an NBFC? Meaning, Full Form & How NBFC Loans Work